Best Airline Credit Cards 2025: Maximize Miles and Perks
If you fly more than a couple of times a year, the right credit card can cut hundreds of dollars off every trip. The best airline credit cards do more than hand you points for groceries and gas. They waive checked-bag fees, grant priority boarding, and sometimes open the door to a lounge on a long layover.
The catch is that not every airline card earns its keep. A card that looks great on paper can quietly lose you money if its annual fee outweighs the perks you actually use, or if you are loyal to an airline the card doesn’t serve. This guide breaks down the cards worth your wallet in 2025, what each one really costs, and how to match one to the way you travel.
How Airline Credit Cards Actually Work
An airline credit card is a co-branded card tied to one airline (or, occasionally, one alliance). Every purchase earns points or miles in that airline’s loyalty program: Delta SkyMiles, United MileagePlus, American AAdvantage, Southwest Rapid Rewards, and so on. Those miles can only be spent, mostly, within that one airline’s ecosystem, which is the single biggest difference between an airline card and a general travel card such as the Chase Sapphire Preferred.
That closed loop is both the strength and the limitation. On the strength side, airline cards carry benefits that general travel cards can’t touch: free checked bags for the cardholder, earlier boarding groups, discounted in-flight purchases, and priority path toward elite status. On the limitation side, your miles are locked up. If you stop flying that airline, the points lose most of their value.
Most airline cards today also earn miles at a flat rate on everyday spending — typically 1x to 2x on restaurants, gas, and groceries — plus a multiplier on purchases made directly with the airline. The real value usually comes from the sign-up bonus and the perks, not from racking up 1x on your coffee runs.
The Best Airline Credit Cards of 2025
These are the cards that consistently deliver the most value relative to their annual fee, based on current welcome offers and benefit structures.
United Explorer Card
The United Explorer Card (issued by Chase) is the classic “workhorse” airline card. Its annual fee is $0 for the first year, then $95. The welcome offer typically lands around 60,000 bonus miles after you spend $3,000 in the first three months — worth roughly $700 toward flights at a modest 1.2 cents per mile.
What makes it stand out is what you get every year, not just at sign-up: a free first checked bag for you and one companion on the same reservation, priority boarding (Group 2), two United Club one-time lounge passes per year, and a $100 statement credit for Global Entry or TSA PreCheck. If you fly United even twice a year with a checked bag, the card pays for itself.
Delta SkyMiles Gold American Express Card
Delta’s Gold card is the best entry point for Delta flyers. The fee is $0 for the first year, then $150. The welcome bonus runs around 40,000 miles after spending a couple thousand dollars, plus the big everyday benefit: a free first checked bag for you and up to eight companions on the same reservation. For a family of four, that single perk is worth roughly $280 per round trip at $35 per bag each way.
You also get a $100 Delta flight credit after spending $10,000 in a calendar year, and Main Cabin 1 priority boarding. The sweet spot here is families and moderate Delta flyers who don’t yet need Sky Club access. Heavy flyers should skip up to the Platinum or Reserve, but Gold is where most people should start.
Citi / AAdvantage Platinum Select World Elite Mastercard
For American Airlines loyalists, the AAdvantage Platinum Select is the value pick. The annual fee is $99, waived the first year. The welcome bonus typically sits at 50,000 bonus miles after $2,500 in spend, and the card throws in a free first checked bag for you and up to four companions, plus preferred boarding.
It earns 2x miles on American Airlines purchases, restaurants, and gas stations, and 1x everywhere else. The effective value is solid for a sub-$100 card, especially once you factor in the 25% savings on in-flight food and beverages and the chance to earn an AAdvantage Loyalty Point boost toward elite status.
Southwest Rapid Rewards Priority Credit Card
Southwest fans should look at the Priority card. Its annual fee is $149, which looks steep until you account for the $75 annual Southwest travel credit and the 7,500-point anniversary bonus — the two together effectively cancel out the fee for anyone who flies Southwest at least once a year. The welcome offer runs around 50,000 points after spending requirements, and Southwest points are famously easy to use with no blackout dates.
The Priority card also comes with four upgraded boardings per year (when available) and tier-qualifying earning toward A-List status. It is the fastest card route to the Southwest Companion Pass, which is one of the best deals in all of travel: a designated person flies free with you for an entire calendar year.
Here is a quick side-by-side of the four cards:
| Factor | United Explorer | Delta Gold Amex | AA Platinum Select | Southwest Priority |
|---|---|---|---|---|
| Annual fee | $95 (waived year 1) | $150 (waived year 1) | $99 (waived year 1) | $149 |
| Typical welcome bonus | ~60,000 miles | ~40,000 miles | ~50,000 miles | ~50,000 points |
| Free checked bags | 1, +1 companion | 1, up to 8 companions | 1, up to 4 companions | 2 bags (no fee) |
| Lounge access | 2 one-time passes/yr | None | None | None |
| Best for | United regulars | Delta families | AA loyalists | Companion Pass chasers |
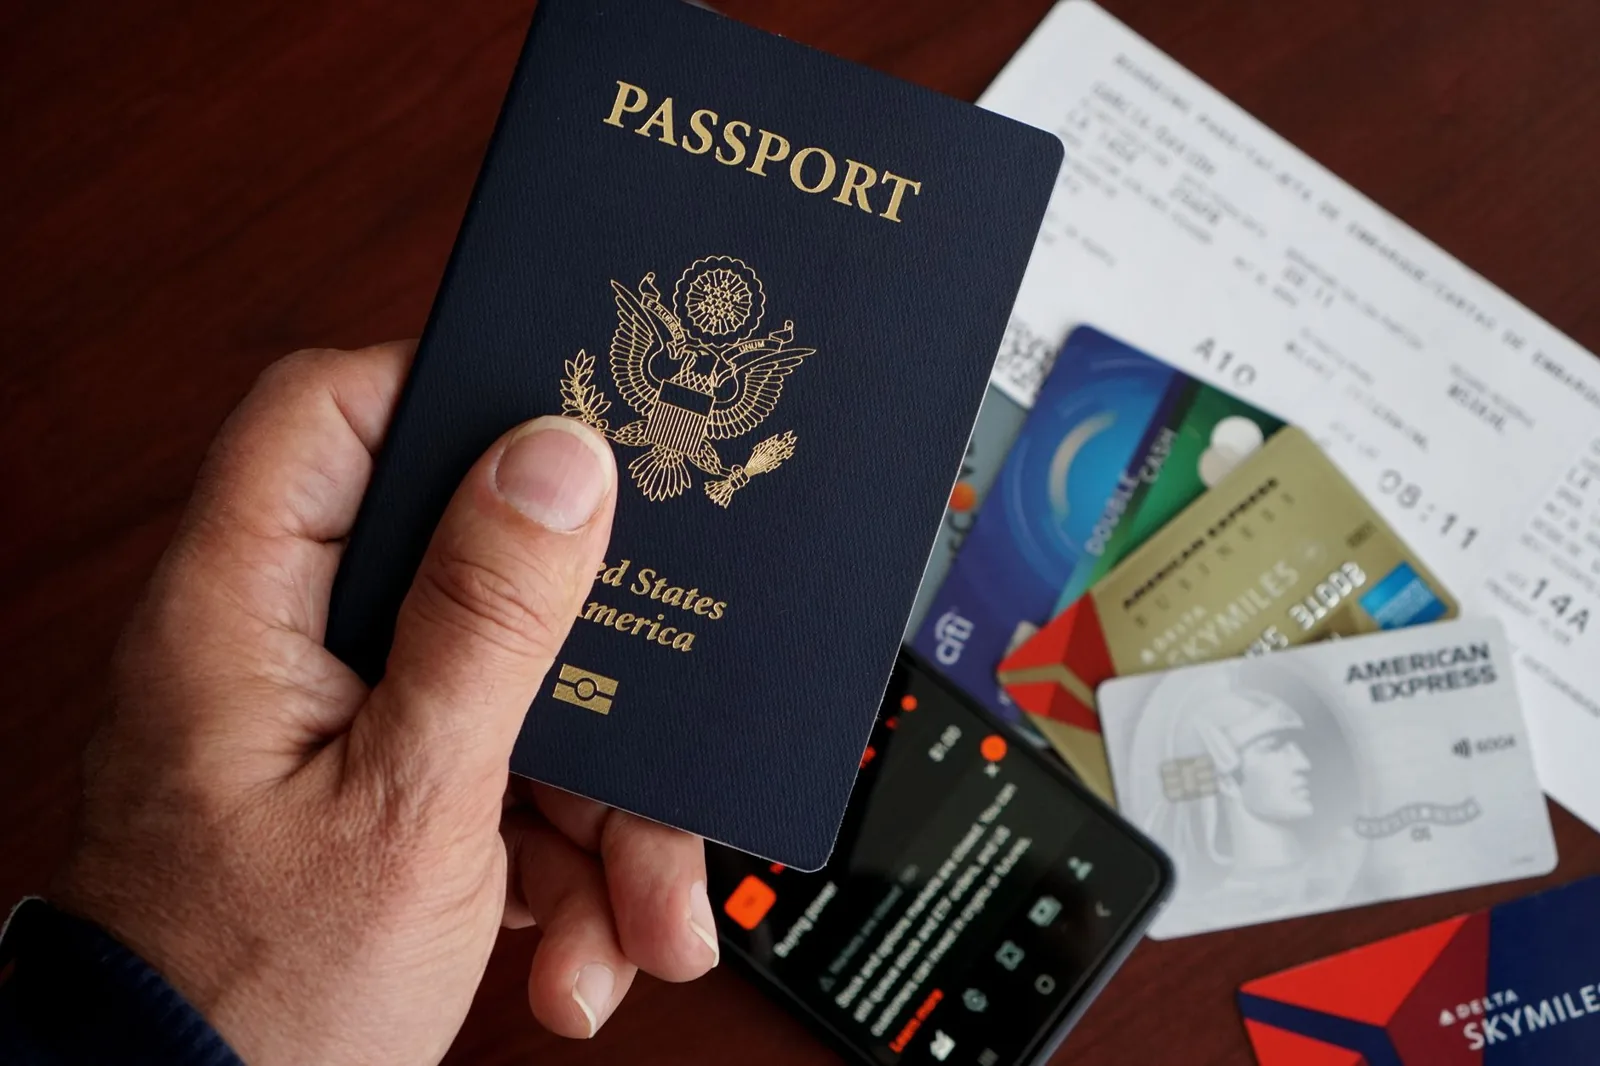
Photo by Pexels via Pexels
Airline Cards vs. General Travel Cards
Airline cards and general travel cards solve different problems, and knowing which one you need will save you from paying two annual fees for overlapping benefits.
A general travel card such as the Chase Sapphire Preferred or Capital One Venture earns flexible points you can transfer to a dozen airline and hotel partners, or simply redeem as cash toward travel. That flexibility is valuable if your loyalty shifts season to season, or you fly a different carrier every trip.
An airline card wins when your loyalty is predictable. If your home airport is a Delta or United hub, or your company books you on the same carrier for every trip, the perks — free bags, priority boarding, lounge passes — are worth real money every single year, not just on redemption. Many travelers who spend a lot on a single airline pair the two: a general card for flexible everyday spending, and one airline card purely for the bag fees and status benefits.
How to Choose the Right Airline Card
Start with your home airport. If you live in Atlanta, Detroit, or Minneapolis, Delta dominates and a Delta card is an easy default. If you are near Newark, Denver, or Houston, United is the natural fit. Phoenix and Dallas skew American; the West Coast leans Alaska and United. Your card should match the airline you can actually fly nonstop most of the time.
Next, do the fee math. Take the annual fee, subtract the value of the perks you will genuinely use, and see if you land in positive territory. A $95 United card that saves you $70 in bag fees on two round trips plus two lounge visits you would have paid for anyway is a no-brainer. A $650 premium card you use for nothing but the welcome bonus is a losing game after year one.
Finally, check the welcome bonus and think about timing. Credit card companies rotate offers, and the same card might run 50,000 miles one month and 80,000 the next. If you have a big purchase coming up — a home repair, a tuition payment, a group trip — the right moment to apply is right before you have that spending ready to hit the minimum spend requirement. If you are planning a specific trip, our guide on the best time to book flights will help you line up the card with a cheaper fare window.
Photo by Pexels via Pexels
Common Mistakes That Cost You Miles
The first mistake is carrying an airline card after you stop flying that airline. Miles sit in the account earning nothing, and the annual fee keeps charging. If your travel patterns shifted, downgrade to the no-fee version of the card rather than closing it outright — closing can dent your credit history.
The second is redeeming miles poorly. Airline miles are typically worth about 1.1 to 1.5 cents each toward award flights, and far less toward statement credits, merchandise, or gift cards. Cashing out 50,000 miles for a $300 gift card when those same miles could buy a $700 flight is a quiet, expensive mistake. Before you redeem, always check the flight booking fees explained so you understand what a “free” award ticket still costs in taxes and fuel surcharges.
The third is hoarding sign-up bonuses without a plan. Every airline card application is a hard inquiry on your credit report. Churning through cards to harvest welcome offers is a legitimate strategy, but only if your credit score and payment discipline can take it. Miss one payment and the interest charges wipe out the value of every mile you earned.
Frequently Asked Questions
Do airline credit cards require good credit?
Yes. Most co-branded airline cards want a good to excellent score, generally a FICO of 670 or higher, with 700-plus giving you the best approval odds and interest rates. If you are building credit, a secured card is a better starting point.
Are airline credit cards worth the annual fee?
It depends on usage. Any card that saves you more in bag fees, credits, and perks each year than its annual fee is worth keeping. For most casual flyers, that math favors the sub-$100 cards over the premium $350–$650 options.
Can I transfer airline miles to another airline?
Usually not directly. Most major US airline loyalty programs do not allow point transfers between airlines, though some belong to alliances (Star Alliance, Oneworld, SkyTeam) that let you redeem miles on partner carriers. A general travel card with transferable points is how you keep flexibility.
Will a credit card get me free flights faster?
The fastest route to a free flight is a welcome bonus, not everyday spend. A 60,000-mile bonus is often enough for a round-trip domestic flight or a one-way international award. You can accelerate that even further by combining the bonus with a cheap international flight ticket strategy on the cash fare.
Do airline cards charge foreign transaction fees?
Some do, some don’t. Many premium and mid-tier airline cards waive foreign transaction fees, but a few entry-level ones still charge 3% on purchases abroad. Check this line item before taking a card overseas.
The Bottom Line
The best airline credit cards pay for themselves through perks you would otherwise buy out of pocket: checked bags, priority boarding, and lounge access. United Explorer is the standout all-rounder, Delta Gold Amex is the family pick, and the Southwest Priority card is the weapon of choice for Companion Pass hunters.
Pick the card that matches the airline you actually fly from your home airport, do the fee math honestly, and apply when a strong welcome bonus is live. If you need a starting point for turning those miles into a cheap trip, see our guide on how to book cheap flights. Done right, one card decision can remove one of the biggest hidden costs of flying.
For the latest welcome offers and current earning rates, check the card comparison tools at The Points Guy and NerdWallet.