Flight Cancellation Refund Policy: How to Get Your Money Back
Every airline publishes a flight cancellation refund policy, but reading the fine print rarely tells you what you’ll actually get back when a trip falls apart. Some cancellations trigger a full cash refund within days. Others leave you holding a travel credit you may never use, minus a fee that eats into the fare you originally paid.
What you recover depends on three things: who cancelled, what fare class you bought, and the airline’s own rules. This guide breaks down exactly how those policies work so you know your rights before you spend a dollar — and what to do the moment a flight you booked goes sideways.
How Airline Flight Cancellation Refund Policies Actually Work
The single most important rule in any flight cancellation refund policy is this: if the airline cancels your flight, you’re owed a full refund — even on a non-refundable ticket. When the carrier fails to get you there, the contract you signed essentially resets. In the US, Department of Transportation rules require airlines to refund the full purchase price, including taxes and fees, when they cancel a flight and you don’t accept an alternative.
The picture changes completely when you cancel. If you back out of a non-refundable fare, the airline keeps the base fare as a penalty, though many will return government taxes and fees. If you bought a refundable ticket, you get your money back minus nothing. And if you cancel within the airline’s 24-hour no-penalty window, US law generally protects you with a full refund regardless of fare type.
The same logic applies to “significant” schedule changes. If an airline moves your flight by several hours or adds a connection you never agreed to, that’s usually treated like a cancellation — you can demand a refund rather than accept the new itinerary. How much of a change counts as “significant” varies by airline, but most define it as a departure shift of two hours or more, or a routing that changes your arrival materially.
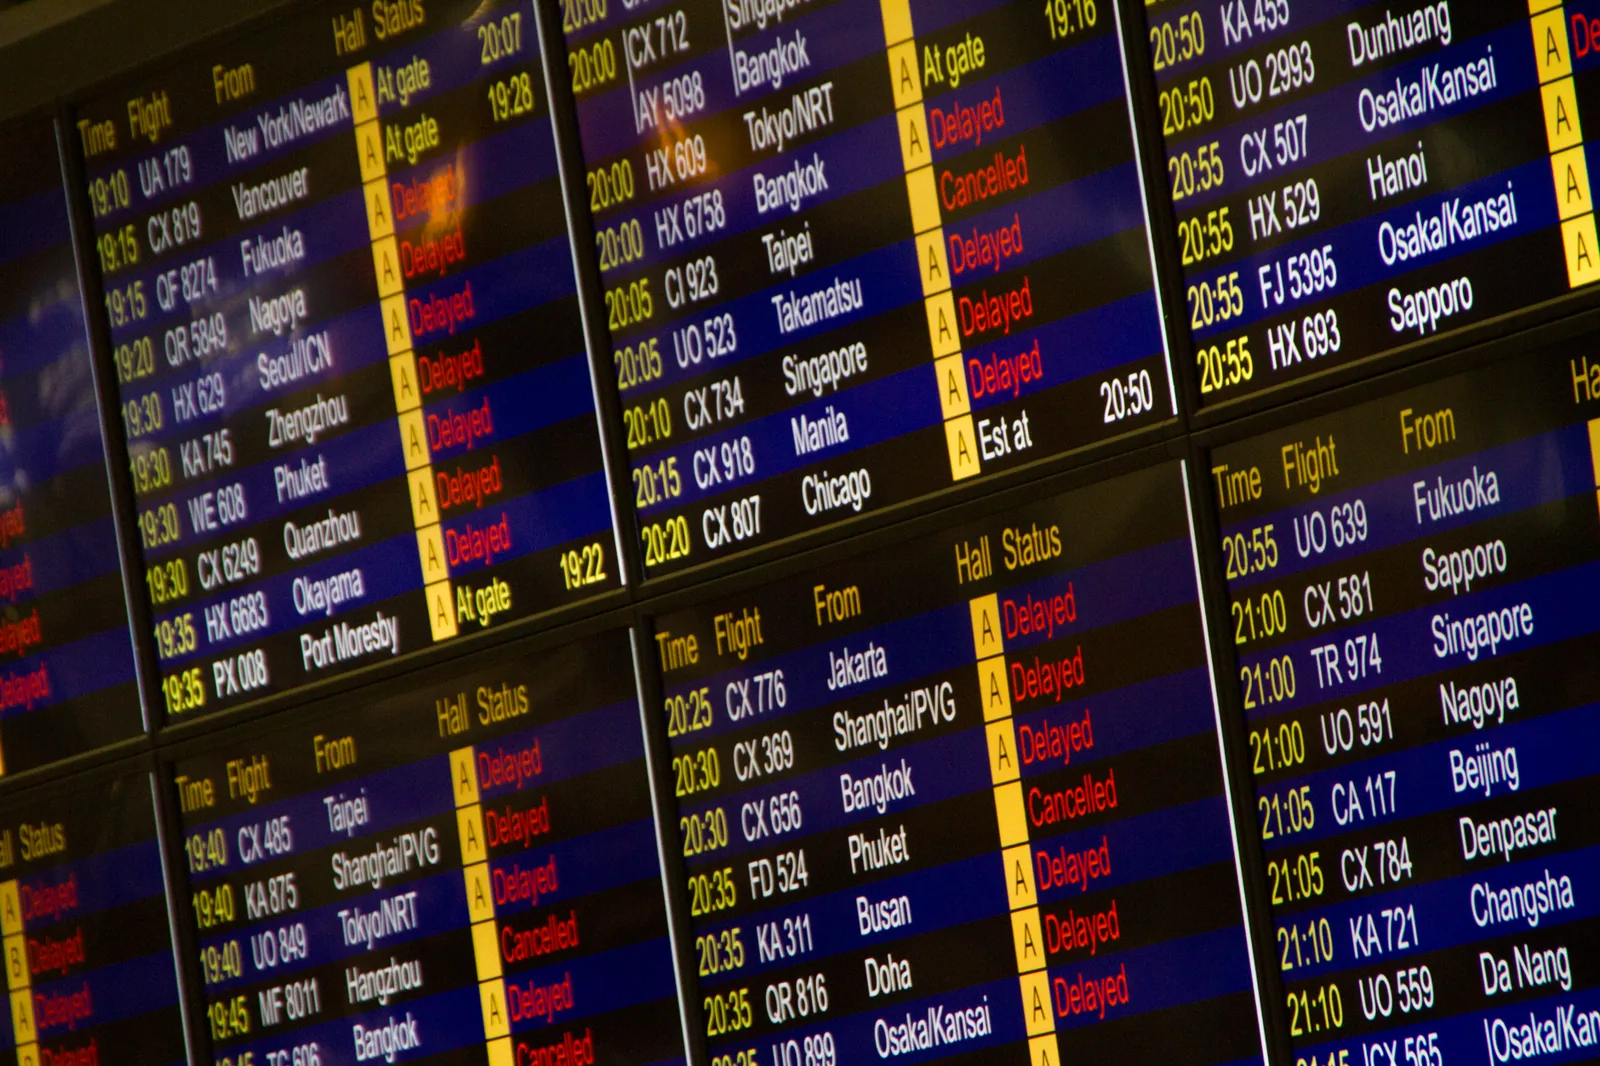
Photo by Oscar Chan via Pexels
What the Law Guarantees: US, UK, EU, and Canada
Your legal rights depend on where your flight operates, not where you live. US travelers get the strongest protection when the airline is at fault.
- United States: Airlines must refund you within seven business days for credit-card purchases and 20 days for cash or check when they cancel or significantly change a flight. This applies even to basic economy and non-refundable fares. The same refund rule covers “significant delays,” though the DOT defines that case by case.
- European Union / UK: Under EC 261 (and the UK’s post-Brexit equivalent), you’re owed a refund or rerouting when an airline cancels, plus cash compensation of €250 to €600 depending on distance when the airline is responsible. Compensation drops to zero if the cause is “extraordinary” — weather, strikes, air-traffic-control failures.
- Canada: The Air Passenger Protection Regulations require a refund to the original payment method for cancellations or long delays within the airline’s control, plus up to CAD 2,400 in compensation for larger carriers.
The catch in every jurisdiction is the fine print on who cancelled and why. A mechanical problem is the airline’s fault. A snowstorm is not. Knowing the difference decides whether you get a refund or just a rebooking.
Photo by Pexels via Pexels
Refund vs. Travel Credit: Know the Difference
Airlines have gotten creative about offering “credits” instead of cash. Here’s how the two options stack up, and when a credit is worth taking.
| Factor | Cash Refund | Travel Credit / Voucher |
|---|---|---|
| Payment method | Original card or in cash | Airline voucher or wallet credit |
| Expiration | N/A — money in hand | Often 12 months, rarely 24 |
| Applicable fares | Refundable tickets, airline mistakes | Non-refundable fares by default |
| Flexibility | Spend anywhere, any airline | Usually same airline, sometimes same route |
| Transferability | N/A | Usually non-transferable, some with fees |
Here’s the practical rule: take cash every time it’s offered. A travel credit locks your money inside one airline, often expires, and can only be used by whoever holds it. You can put cash toward any future trip with any carrier — often at a better price. Non-refundable fares don’t always give you a choice, but when they do, don’t let the airline frame a voucher as doing you a favor.
One exception: if an airline offers a credit worth more than your fare as an incentive — a common practice now — the math can favor the voucher. Just confirm the expiration date and blackout dates in writing before you accept. If you’re shopping for new fares to apply that credit, see our guide on how to book cheap flights to stretch it further.
What You’re Actually Owed by Fare Type
The fare you bought dictates almost everything once you cancel. Here’s the reality across the common ticket types.
- Basic economy: Near-zero flexibility. Cancel and you typically forfeit the entire fare; some airlines allow a “cancel for credit” that subtracts a $99 to $199 fee. The 24-hour rule is your only real safety net.
- Standard non-refundable (main cabin): You lose the base fare but most US carriers credit the value toward a future flight, minus a cancellation fee that ranges from $0 (Southwest) to $199 (Delta for some international routes). Change fees are increasingly waived on domestic main-cabin fares at American, Delta, and United.
- Refundable / flexible: Full cash refund to your original payment method, no fee, no debate. These tickets cost more upfront — sometimes 30 to 50% more — which is why they’re worth it only for trips you might cancel.
- Premium (business/first): Policies vary wildly by airline and route. Some premium fares are fully refundable; others carry fees of $400 or more. Always check the specific fare rules, since premium doesn’t automatically mean flexible — our business-class vs. economy cost comparison covers the trade-offs.
For detailed breakdowns of what airlines tack on top of your fare, including change and cancellation charges, read our explainer on flight booking fees.
How to Claim a Refund: A Step-by-Step Playbook
Act fast and document everything. The window for a clean refund can close while you wait on hold.
- Capture the cancellation notice — screenshot the email, app notification, or gate announcement with the time and date. This is your proof of who cancelled.
- Check the fare rules — pull up your booking confirmation and read the fare class’s cancellation terms and the airline’s refund page before you click anything.
- Request online first — most US carriers let you request a refund through their website or app in minutes, which generates a case number you can track.
- Say no to the automatic credit — if the airline rebooks you or issues a voucher without asking, explicitly reject it and demand a refund to your original payment method.
- Escalate with the card, not the hold line — if the refund hasn’t posted within the DOT’s seven-business-day window, dispute the charge with your credit-card issuer and file a complaint with the Department of Transportation. Both are free and surprisingly effective.
- Keep every reference number — airline case IDs, chargeback numbers, and complaint tracking codes in one place.
Major US Airlines at a Glance
Policies converge on the big points but differ on the margins. Here’s the current landscape for the four carriers Americans book most.
| Airline | 24-Hour Cancel | Change/Cancel Fee | Refundable Fares | Standby Perks |
|---|---|---|---|---|
| Southwest | Free within 24h | $0 — always | N/A (all fares flexible) | Free same-day changes |
| Delta | Free within 24h | $0 on domestic main cabin | Yes, higher fare | Same-day confirmed for a fee |
| American | Free within 24h | $0 on most domestic | Yes | Priority via status |
| United | Free within 24h | $0 on most US/Canada | Yes | Same-day change option |
The standout is Southwest, which has no change or cancellation fees on any fare — you always receive the fare’s value as flight credit, even on its cheapest Wanna Get Away tier. The big three legacy carriers now match that flexibility on most domestic main-cabin tickets, which makes the old “$200 change-fee” era largely a thing of the past for everyday flyers.
How to Protect Yourself Before You Book
The best flight cancellation refund policy is the one you never have to invoke. A few habits turn a potential loss into a recoverable expense.
- Book with a card that covers trip cancellations. Chase Sapphire Reserve and Capital One Venture X, for example, reimburse up to $10,000 per trip (Sapphire) for covered reasons like illness or severe weather. Check your specific card’s benefit guide.
- Buy travel insurance for expensive or international trips — expect to pay 4 to 10% of your trip cost. Look for “cancel for any reason” coverage if you want full control, which itself usually reimburses only 50 to 75%.
- Use the 24-hour rule strategically. US law requires airlines to let you cancel within 24 hours of booking (if booked at least seven days out) with no penalty. It’s a free way to lock a fare while you finalize plans.
- Read the fare class before you click “pay.” The fare rules are one click away and spell out exactly what cancellation will cost you.
When you’re ready to book, timing matters more than most travelers realize — our guide on the best time to book flights shows how a well-chosen booking window can both save money and buy you cancellation flexibility.
Frequently Asked Questions
Does every airline have a 24-hour cancellation refund?
In the US, yes — federal rules require airlines that sell tickets in the United States to allow a full refund within 24 hours of booking if the ticket was purchased seven or more days before departure. Some airlines voluntarily extend this to shorter windows.
Can I get a refund if the airline cancels my flight?
Always. If the airline cancels or significantly changes your flight and you don’t accept its alternative, you’re entitled to a full refund to your original payment method — including on non-refundable and basic economy fares. You don’t have to accept a travel credit instead.
How long does a flight refund take?
The US DOT requires refunds within seven business days for credit-card purchases and 20 days for cash or check. In practice airlines often issue card refunds within three to five days, but the institution that issued your card can add time to post it to your statement.
Do I get a refund if I’m sick and can’t fly?
Only if you bought a refundable fare or a travel-insurance policy with a medical reason, or if you hold a credit card with trip-cancellation protection. A non-refundable ticket alone won’t refund you for illness — you’ll typically receive flight credit minus any applicable fee at best.
What’s the difference between a refund and a flight credit?
A refund returns your money to your original payment method and can be spent anywhere. A flight credit is airline-specific money — often expiring within 12 months, generally non-transferable, and usable only on the issuing carrier. Unless the airline sweetens the credit with extra value, cash is the better deal.
For your rights as a passenger, the U.S. DOT explains cancelled and delayed flight rules.
The Bottom Line
Know the flow, because it never changes: if the airline cancels, you get your money back — period, on any fare. If you cancel, your fate is set by the fare class, the 24-hour rule, and whether you bought refundable flexibility or trip protection. Cash beats credits whenever you have the choice, and a fat travel-rewards card plus a modest insurance policy turns most surprise cancellations from a total loss into a recoverable cost.
Before your next booking, spend sixty seconds on the fare rules and another on the airline’s refund page — book cheap flights smartly today, and you’ll spend those sixty seconds once, not in a panic at the gate.